Credible vs LendingTree (2026): Which Gets the Best Rate?

Get the weekly rate update — top HYSA, CD, and mortgage rates every Sunday.
Every Sunday · No spam · Unsubscribe anytime
Disclosure: This post contains affiliate links. If you sign up through these links, we may receive a commission at no extra cost to you. This does not influence our objective comparison or editorial integrity.
Last Updated: March 3, 2026
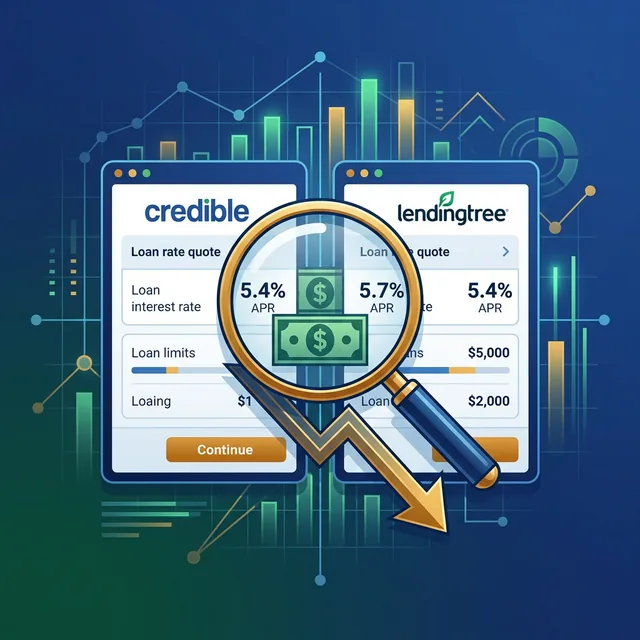
Here’s something that bothers me about the loan marketplace industry: both Credible and LendingTree advertise the exact same promise—“find your lowest rate in minutes”—but they operate with fundamentally different philosophies. And that difference matters far more than most borrowers realize.
The platform you start with can shape the offers you see, and even a small APR difference adds up. On a $28,000 consolidation loan over 5 years, the gap between a 10% and an 11% APR is about $830 in total interest paid. Not trivial.
[!NOTE] Quick Takeaways:
- Credible is curated: Fewer lenders, but they’re pre-vetted premium partners—expect less inbox spam and cleaner UX.
- LendingTree is a network: 300+ lending partners means more offers, but also more aggressive marketing follow-up.
- Soft pull on both: Neither platform runs a hard inquiry to show you initial rates.
- The email problem is real: LendingTree’s model depends on lender competition; that competition often lands in your inbox as a flood of emails.
- The “winner” depends on your profile: High-credit borrowers may get marginally better rates on Credible; thin-file or fair-credit borrowers may get more options via LendingTree.
How the Marketplace Model Actually Works
Before we compare, let’s acknowledge how these platforms make money—because it shapes everything about the experience.
Both Credible and LendingTree are lead generation businesses. You submit your financial profile, they pass it to partner lenders, and those lenders pay a fee for the opportunity to compete for your business. The difference is in how they manage that competitive process.
Credible’s “Pre-Approval Marketplace” Model
Credible, acquired by Fox Corporation in 2019, operates more like a curated boutique. Their lender list for personal loans is deliberately small—typically 17 to 25 partners, depending on your state and loan type. The benefit? Every offer you see is a real pre-approval, not a bait-and-switch estimate.
Credible’s prequalified rates come from its lender partners’ own quotes, so they tend to track the final offer more closely than an estimate would. Rates always depend on the final underwriting, so treat any displayed rate as an estimate until the lender confirms it.
LendingTree’s “Auction House” Model
LendingTree, founded in 1998, is the granddaddy of loan marketplaces. They connect borrowers to 300+ lenders across every loan type imaginable—student loans, auto, mortgages, personal loans, business financing. More lenders competing should drive rates down, and sometimes it does.
But here’s where it gets complicated. Many of the “lenders” in LendingTree’s network are themselves brokers or aggregators. A single LendingTree submission can generate multiple offers, plus a steady stream of email follow-ups within days. That’s not a bug—it’s the business model.
The Rate Reality: Side-by-Side Numbers
Let me be direct about what matters here, because the headline APR rates you see advertised don’t tell the whole story.
| Feature | Credible | LendingTree |
|---|---|---|
| Lender Partners (Personal Loans) | ~17-25 | 300+ |
| Soft Pull Available | ✅ Yes | ✅ Yes |
| Rate Match Accuracy | Tends to be higher | Tends to be lower |
| Marketing Email Volume | Lower | Higher |
| Loan Range | $1,000–$100,000 | $1,000–$50,000 |
| Loan Types Covered | Personal, Student, Mortgage, Refi | Personal, Student, Mortgage, Auto, Business |
| Founded / Ownership | 2012 / Fox Corp | 1998 / Public Co. |
Rate match accuracy is the thing to watch. After a platform shows you 6.9% APR, does the funded loan actually close at 6.9%? Credible’s curated model tends to do better here. LendingTree’s pre-qualification offers can adjust upward after the full underwriting process.
The Spam Factor: An Honest Assessment
Okay, real talk. This is the thing nobody wants to admit openly, but it’s a common complaint in public reviews of both platforms.
Credible: After submitting your profile, expect a small number of follow-up emails from Credible itself. The lenders in their network tend to contact you less aggressively. Many reviewers describe the experience as “clean.”
LendingTree: Brace yourself. After a LendingTree submission, it’s common to hear from multiple lenders within days via email and phone. This is baked into their business model—lenders pay for the lead and want to monetize it aggressively.
Consider a hypothetical borrower, a 38-year-old warehouse manager, who refinances $22,000 in credit card debt through LendingTree. Suppose he receives a quoted rate of 8.4% versus the 11.2% he was previously paying—a potentially meaningful reduction, though individual outcomes vary based on creditworthiness and lender decision at the time of full underwriting. But he might also receive dozens of emails and several phone calls in the following week from various lenders he hadn’t chosen. He could still use the platform again, but through a dedicated email address.
The Fiscal Realist Takeaway: Use a dedicated email address (not your primary one) when submitting on LendingTree. Create a free Gmail or Proton Mail account first, then check it selectively.
Loan Type Coverage: Where Each Platform Wins
This is an underrated consideration. Not all loan marketplaces are equally good at every loan type.
Credible’s Sweet Spot: Student Loans and Refi
If you have federal student loans you’re considering refinancing (a complex decision with significant trade-offs—more on this in a future guide), Credible is the clear leader. Their student loan refi vertical is deep, and they work with ELFI, NaviRefi, Laurel Road, and SoFi—all reputable partners.
For personal loan debt consolidation in the $10,000-$50,000 range with a credit score above 680, Credible may be worth starting with given its curated lender network and tendency toward rate quotes that stay close to the final offer. Individual results will vary based on your credit profile, state of residence, and lender policies at the time of application.
LendingTree’s Sweet Spot: Mortgages and Fair Credit Profiles
For home purchase mortgages and home refinancing, LendingTree’s massive lender network is genuinely valuable—especially for borrowers in smaller markets where local credit unions don’t appear on Credible’s panel.
And here’s the thing most people miss: if your credit score is between 580 and 650, LendingTree may actually return more usable offers. Some of their 300+ partners specialize in non-prime lending that Credible’s curated network doesn’t touch.
What Happens After You Click “Check Rates”
This is the step most reviewers skip, and it’s where the real differences emerge.
On Credible: After your soft pull, you’re shown a table of offers sorted by either APR or monthly payment. Each offer links directly to the lender’s pre-filled application. The process is sequential—you pick one, you apply. Clean, manageable, and transparent.
On LendingTree: After your soft pull, you may see several offers simultaneously. Each lender has their own follow-up sequence. LendingTree’s platform also shows you “My LendingTree,” a personal finance dashboard with credit monitoring—a value-add, but also a vehicle for continued cross-selling.
[!TIP] Whichever platform you use, always check the lender’s full terms page before submitting the hard-pull application. The displayed rate on a marketplace is always a pre-qualification estimate. Your actual rate depends on the full underwriting review.
The Real Answer: Use Both, in the Right Order
Here’s a strategy the marketing for both platforms doesn’t highlight—using them together takes little time and, depending on your profile, may help you identify meaningful rate differences across lenders. Savings potential varies widely.
The Two-Platform Protocol:
- Start with Credible for your baseline (clean UX, reliable rate quotes)
- Then run LendingTree with a burner email to see if any of their 300+ lenders beat your best Credible offer
- Use the LendingTree offer as leverage (call the Credible lender and ask if they match)
- Go with the lower APR after calculating total interest paid (use Bankrate’s loan calculator)
In practice, the final rates from the two platforms are often close, though one will occasionally produce a meaningfully better offer, and which one varies by borrower.
Translation: Neither platform “wins” consistently. Your credit profile, loan amount, and state of residence matter more than the brand.
The Daily Fiscal Verdict
For borrowers with strong credit (680+) seeking personal loans: Start with Credible. The curated network, reliable rate quotes, and clean post-application experience make it the superior entry point. You’ll see offers from a curated lender panel without drowning in marketing.
For borrowers with complex profiles (fair credit, larger loan needs, mortgage shopping): Give LendingTree a serious look. Yes, manage your inbox expectations. But 300+ lenders competing for your business is a genuine structural advantage when your profile doesn’t fit the “prime borrower” mold.
The Uncomfortable Truth: Neither of these platforms is a substitute for calling your credit union directly. In 2025-2026, some credit unions have been offering personal loan rates that may compare favorably to marketplace quotes—particularly for established members with direct deposit relationships. Rates vary by institution and individual profile. The marketplace may serve as baseline context, not necessarily your final decision.
Rate shopping across platforms, credit unions, and your current bank—all within a 14-day window—generates only a single hard inquiry impact (FICO treats multiple rate inquiries for the same loan type within 14-45 days as a single inquiry). Use that window strategically.
Your 7-Day Rate Shopping Plan
- Day 1 (Morning): Pull your free FICO score from Experian, Equifax, or your credit card. Know your exact number before you start.
- Day 1 (Afternoon): Submit to Credible’s soft-pull form. Screenshot or download your best 3 offers.
- Day 2: Create a dedicated email address. Submit to LendingTree’s form. Compare offers to Credible’s.
- Day 3: Call your primary credit union or bank directly. Ask for their current personal loan rate for your profile. Give them the number from your best marketplace offer.
- Day 4: Research the top 2-3 lenders from your search. Check recent reviews on Trustpilot (2025-2026 only). Look specifically for “hard inquiry bait-and-switch” complaints.
- Day 5-6: If you have a margin of $800+ in interest savings, submit the formal application with the winning lender.
- Day 7: Confirm origination fee terms in writing before signing. The rate shown at soft-pull is an estimate. The rate on the promissory note is the contract.
[!TIP] Compare Secured vs. Unsecured Costs: If home equity is an option you’re considering, our HELOC vs. Personal Loan Comparator models the true interest cost difference—including variable-rate stress scenarios and collateral risk—so you can compare both paths before committing.
Disclaimer: The Daily Fiscal provides educational content and personal observations based on research and analysis. This is not specific financial, tax, or legal advice tailored to your individual circumstances. Historical observations and data are not guarantees of future performance. All investing involves risk, including the potential loss of principal. Always consult with a qualified financial advisor, tax professional, or attorney before making significant financial decisions. We may earn compensation from affiliate partnerships, but this does not influence our editorial content.
Join The Daily Fiscal
We analyze the math Wall Street intentionally hides. Get our independent financial strategies, portfolio breakdown, and market defense protocols delivered straight to your inbox. No fluff.
Free forever. Unsubscribe anytime.
Shikhar Johari
Founder & Lead Analyst | 12+ Years in Institutional Finance Technology
Shikhar Johari founded The Daily Fiscal after 12+ years building financial technology systems at US asset management firms — including trading infrastructure, portfolio analytics platforms, and retail investor tooling. He writes about brokerage and bank comparisons, taxes, and retirement accounts, relying on primary sources (SEC filings, fund prospectuses, FDIC data, IRS publications, and each provider's published fee schedule). All content is educational and does not constitute personalized investment, tax, or legal advice.
Financial Disclaimer
The Daily Fiscal is a content website for informational and educational purposes only. Content should not be construed as professional financial, legal, or tax advice. Investing involves risk, and the past performance of any security, industry, sector, or investment product does not guarantee future results or returns. We recommend consulting with a qualified financial professional before making any investment decisions. TheDailyFiscal.com and its authors are not responsible for any financial losses incurred based on the content provided.
KEEP READING.
View All Articles → Personal Finance
Balance Transfer vs Personal Loan 2026: Pay Off Debt Faster
The interest math on a 0% APR balance transfer vs a fixed-rate personal loan. The winner depends entirely on your repayment timeline and discipline.
 Personal Finance
SoFi vs Upstart (2026): Best Loan for Fair Credit?
SoFi wants high credit scores. Upstart uses AI to approve borrowers that banks reject. Here's how the interest math compares across credit tiers.
 Personal Finance
Lifestyle Creep: How Every Raise Disappears (And How to Stop It)
Lifestyle creep is why most people never build wealth despite earning more each year. Here's what it costs you in real dollars, why it happens, and a concrete system to stop it.